





5052 Aluminum: O, H32 or H34, Bend Radius and Buying Mistakes
5052 aluminum sheet in O, H32 and H34 tempers differs clearly in strength, ductility...


Drewry's Intra-Asia Container Index (IACI) closed on 24 September 2026 at 1,491 USD per 40ft container, up 6% on the week and at an all-time high for the fifth week in a row. That is almost 34% above the 1,114 USD/40ft recorded in early June 2026. The spike lands exactly as China enters its double holiday: Mid-Autumn Festival on 25–27 September and National Day on 1–7 October. For companies importing aluminium sheet and coil from China into Hai Phong, this is the main story of week 39, because aluminium ingot prices were flat while the cost of moving the metal went up.
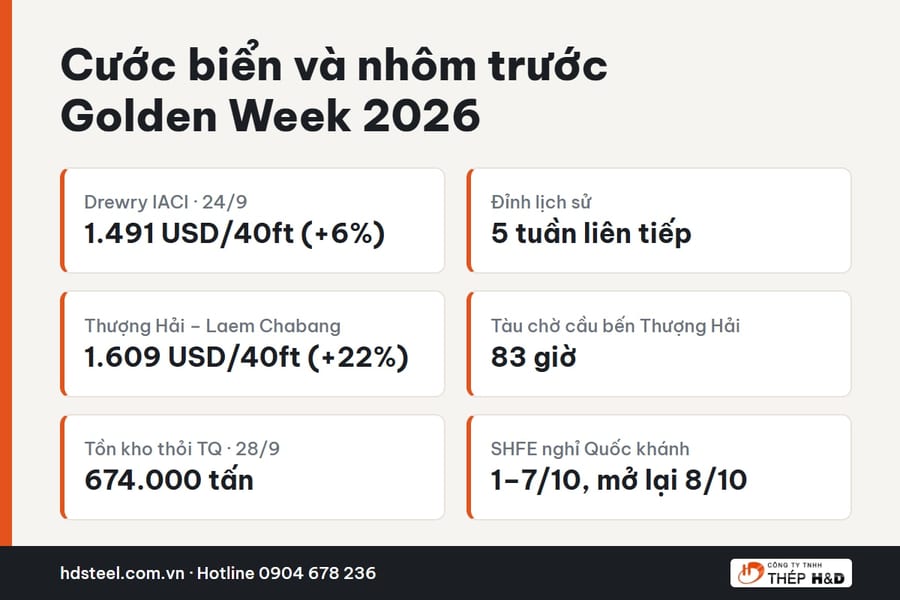
Key figures on intra-Asia freight and aluminium ingot before China's National Day holiday (compiled by H&D Steel)
According to Drewry, the IACI covers 18 intra-Asia lanes and excludes terminal handling charges. In the week to 24 September, Shanghai–Laem Chabang (Thailand) jumped 22% to 1,609 USD/40ft and Shanghai–Jakarta rose 12% to 2,300 USD/40ft. Drewry points to four overlapping causes: shippers rushing cargo out before Golden Week; a string of typhoons in East Asia that pushed average berth waiting time to 83 hours in Shanghai and 38 hours in Ningbo; Middle East tensions; and a fire at Jakarta's NPCT1 terminal on 21 September. Drewry's view is that intra-Asia rates should level off over the following weeks, not that they will fall.
An Asian container terminal before China's National Day holiday — AI-generated illustration
On the same day, Drewry's World Container Index (WCI) for East–West trades fell 1% to 4,468 USD/40ft: Shanghai–Los Angeles rose 2% to 7,838 USD/40ft while Shanghai–Rotterdam dropped 4% to 3,485 USD/40ft. For East–West lanes Drewry expects further declines ahead of Golden Week. In short, freight to the US and Europe is cooling, but the short Asian legs, including the route that brings aluminium to Vietnam, remain hot.
Blank-sailing counts also depend on who is counting. Drewry's Cancelled Sailings Tracker of 25 September lists 58 cancellations for weeks 40–44 (28 September – 1 November), or 8% of the schedule; its 18 September edition had 77 cancellations for weeks 39–43, or 11%. Xeneta and eeSea data quoted on 24 September put just under 13% of October capacity from Asia to the US and Europe as blanked, against 18–21% in the same period of 2025. The three figures do not contradict each other; they use different windows and denominators. The common message is that the 2026 cuts are milder than in previous years and concentrated on US and Europe services, not on intra-Asia lanes.
In China, the SMM A00 ingot price stood at 24,240 CNY/t on 24 September (including 13% VAT). Ingot inventory in the main consuming areas fell by 63,000 tonnes in the week to 17 September and by another 55,000 tonnes in the week to 24 September, 118,000 tonnes in total, down to 678,000 tonnes; by 28 September it was 674,000 tonnes. SMM statistics for 2020–2025 show that ingot stocks typically rise by 4.0–17.3% during the National Day week, because smelters keep casting while rolling and extrusion plants close. SMM also flags the risk of concentrated arrivals after the holiday and expects SHFE aluminium to trade between 23,800 and 24,300 CNY/t and LME between 3,150 and 3,250 USD/t over the break. SHFE is closed on 1–7 October and reopens on 8 October, leaving only three reference sessions from 28 to 30 September.
Need a quote for aluminium sheet or coil for October delivery? See our aluminium sheet A1050, A3003, A5052, 6061 and aluminium coil and slit strip pages, or contact H&D Steel: hotline/Zalo 0904 678 236 (Sales Department). Please include alloy, thickness, width, temper and quantity for an accurate quote.
5052 aluminum sheet in O, H32 and H34 tempers differs clearly in strength, ductility...
Shanghai reopened after National Day with two down sessions: the SMM A00 aluminium in...
From 20 October 2026, Decree 344/2026/ND-CP opens a state ordering mechanism and ince...
Aluminum's physical figures differ between alloys, and each figure drives a concrete...
The SMM A00 aluminium ingot price fell in all three sessions of week 40/2026, closing...
Vietnam's car market sold 432,548 vehicles in the first eight months of 2026, the fas...
3mm aluminum sheet is the most requested thickness in the thin-to-medium range: stiff...
A6061 is a heat-treatable aluminium–magnesium–silicon alloy widely used for machine f...
Drewry's Intra-Asia Container Index closed at 1,491 USD/40ft on 24 September 2026, up...
The SMM A00 aluminium ingot price ended week 39/2026 at 24,240 CNY/t, up 60 CNY/t fro...


