





5052 Aluminum: O, H32 or H34, Bend Radius and Buying Mistakes
5052 aluminum sheet in O, H32 and H34 tempers differs clearly in strength, ductility...


On the macro front, the US inflation data for March, including CPI and PPI, were higher than expected, dampening expectations for a near-term interest rate cut by the Federal Reserve. The US dollar index strengthened, putting pressure on base metal prices. Recently, the signal of tariff implementation on Russian aluminium has been strengthening, which may cause market disturbances. Investors should pay close attention to subsequent macro developments.
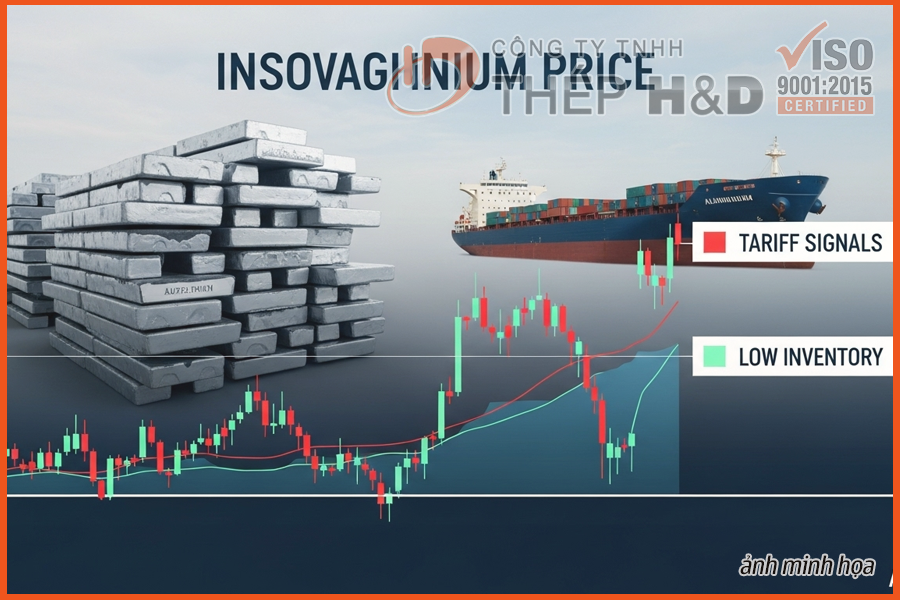
On the supply side: The resumption of aluminium production in Yunnan province after the dry season is progressing slowly. New production capacity is limited, and domestic aluminium output is expected to see slow growth in April. The global primary aluminium production in February 2025 stood at 5.895 million tonnes.
On the inventory side: LME and domestic (SHFE) aluminium ingot inventories are at historically low levels for the same period. As of April 11, the social inventory of aluminium ingots in China's 8 major markets was 849,000 tonnes, a decrease of 11,000 tonnes from the previous week. Low inventory provides strong support for aluminium prices.
On the demand side: The operating rates of downstream processing enterprises were stable. Downstream consumption was stable but lacked strong growth. Processing enterprises maintained operations, with steady demand for products like aluminum coils and aluminum sheets. However, demand for more specific applications such as aluminum checkered plates in construction and aluminum round bars in machining varied by sector.
In the East China market, the spot price was at a premium of about 20 yuan/mt over the SHFE front-month aluminium contract. Sellers held firm on prices due to low inventory. In the Central Plains (Gongyi) market, the spot price was at a discount of about 130 yuan/mt against the SHFE contract. In the South China market, the spot premium was around 20-40 yuan/mt, with transactions mainly occurring among traders.
In summary, low domestic and overseas aluminium inventories continue to provide strong support for prices. However, the recovery in downstream consumption is not yet robust. The market is sensitive to macro news and policy information. It is expected that aluminium prices will continue to fluctuate at high levels. The SHFE aluminium contract is anticipated to trade between 19,800-20,500 yuan/mt, while LME aluminium will likely range between $2,450-2,550/mt.
Source: ALCircle
5052 aluminum sheet in O, H32 and H34 tempers differs clearly in strength, ductility...
Shanghai reopened after National Day with two down sessions: the SMM A00 aluminium in...
From 20 October 2026, Decree 344/2026/ND-CP opens a state ordering mechanism and ince...
Aluminum's physical figures differ between alloys, and each figure drives a concrete...
The SMM A00 aluminium ingot price fell in all three sessions of week 40/2026, closing...
Vietnam's car market sold 432,548 vehicles in the first eight months of 2026, the fas...
3mm aluminum sheet is the most requested thickness in the thin-to-medium range: stiff...
A6061 is a heat-treatable aluminium–magnesium–silicon alloy widely used for machine f...
Drewry's Intra-Asia Container Index closed at 1,491 USD/40ft on 24 September 2026, up...
The SMM A00 aluminium ingot price ended week 39/2026 at 24,240 CNY/t, up 60 CNY/t fro...


