091 327 0770 - 090 326 2566
info@hdsteel.com.vn

U.S. Expands Critical Minerals List: Far-Reaching Implications for Supply Chains and Trade Policy

U.S. critical minerals list expands, impacting global supply chains

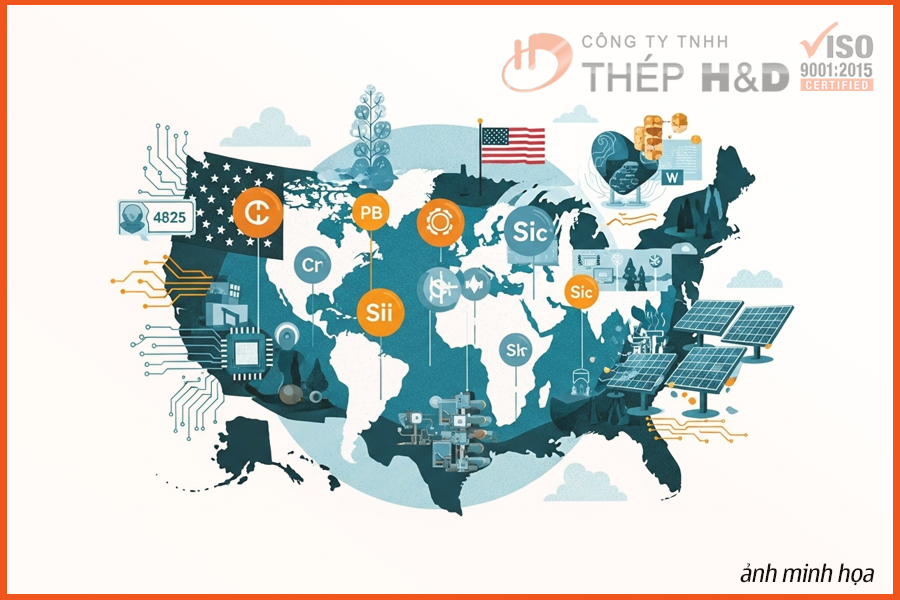
Washington D.C., September 10, 2025 – The U.S. Department of the Interior, through the U.S. Geological Survey (USGS), has unveiled a significantly expanded 2025 critical minerals list, growing from 50 to 54 minerals. This strategic move reflects Washington's escalating prioritization of supply chain security and economic resilience amidst geopolitical tensions and rapidly evolving technological demands. The addition of six new minerals – potash, silicon, copper, silver, rhenium, and lead – alongside the removal of arsenic and tellurium, marks a pivotal shift in the nation's resource policy.

Key Changes and New Methodology

This revision of the list is not merely a numerical adjustment but a methodological advancement. The 2025 list is underpinned by a new, more sophisticated economic model developed by the USGS. This model focuses on assessing the potential supply chain disruption risks that foreign trade issues could pose to the U.S. economy. By quantifying economic effects and prioritizing minerals by their disruption risk, the U.S. is adopting a more data-driven and comprehensive approach to identifying materials essential for national security and industrial development.

The newly added minerals are all integral to various strategic industries:

  • Potash: Crucial for agriculture and fertilizer production, ensuring food security.
  • Silicon: A foundational element for the semiconductor, electronics, and solar industries.
  • Copper: An essential industrial metal for infrastructure, electronics, renewable energy, and electric vehicles.
  • Silver: Now recognized as strategically critical for national security, clean energy technologies, AI, electronics, and defense.
  • Rhenium: A superalloy metal used in jet engines and gas turbines.
  • Lead: Important in batteries, ammunition, and other industrial applications.

Conversely, the removal of arsenic and tellurium from the list indicates a re-evaluation of their risk profile or a shift in their strategic necessity.

Strategic Rationale Behind the Expansion

The decision to expand the critical minerals list is driven by several key strategic factors:

  1. Supply Chain Security: The U.S. heavily relies on imports for many of these minerals. Designating them as 'critical' enables the government to implement measures to reduce this dependency, especially from geopolitically sensitive sources, thereby mitigating risks of trade disruptions and economic harm.
  2. Growing Strategic Importance: Minerals like silver and copper are increasingly recognized for their indispensable roles in emerging technologies and defense applications. Silver, for instance, is a vital component in solar panels, electric vehicles, and advanced electronics, while copper is the backbone of global electrification.
  3. National Infrastructure and Technological Advancement: The newly added minerals are foundational for building and maintaining modern infrastructure, from smart grids to advanced transportation systems. They also drive innovation in sectors such as artificial intelligence and renewable energy.

Far-Reaching Implications for Industry and Policy

The expansion of the U.S. critical minerals list carries significant implications for investors, managers, and technical experts globally:

  • Tariff and Trade Policy Leverage: With expanded critical mineral designation, the U.S. could implement targeted trade measures, including tariffs or tariff relief, to protect domestic supply chains and encourage domestic mining and processing. This could create a new playing field for domestic producers and influence global pricing.
  • Enhanced Funding and Regulatory Support: Critical mineral status often leads to greater federal funding, streamlined permitting, and official stockpiling programs. This is particularly crucial for metals like silver and copper, where securing domestic production is a high priority. Mining and processing companies may see new opportunities for government support.
  • Supply Chain Security Reinforcement: The updated list underpins strategies to reduce dependence on foreign sources, particularly from geopolitically sensitive regions. This will foster diversification of supply and investment in advanced extraction and recycling technologies.
  • Market and Investment Impact: The inclusion of silver, copper, and other industrial minerals signals significant long-term demand increases due to their roles in clean energy technologies and infrastructure modernization. This is expected to attract investor interest and drive focus within the mining and processing sectors. Investors should consider companies well-positioned to benefit from these policy shifts.

As mandated by the U.S. Energy Act of 2020, periodic reassessment of mineral criticality is required, reflecting a recognition that the evolving technological landscape demands frequent re-evaluation. The National Mining Association (NMA) has applauded the expansion, while also emphasizing that many critical minerals are co-produced with other materials, such as aluminum – the material for modern and future industries, suggesting the need for policies to be broadly applicable to all U.S. mined materials.

Conclusion

In summary, the 2025 critical minerals list expansion reveals a heightened U.S. emphasis on securing supply chains for minerals fundamental to economic security, national defense, and technological leadership. These changes will have significant consequences for trade policy, domestic mining incentives, and industry strategic planning, shaping the future of critical industries for decades to come.

References:

  • Reuters (2025). U.S. critical minerals list expands ahead of possible tariffs.
  • U.S. Geological Survey (USGS). Department of the Interior releases draft 2025 List of Critical Minerals. 
  • NMA (National Mining Association). NMA Applauds Expansion of USGS Critical Minerals List. 
  • USAGOLD. Silver Gains Strategic Status: US Proposes Critical Minerals Designation Amid Supply Concerns.

Bài viết liên quan

Nhôm A5052: chọn O, H32 hay H34, bán kính chấn và lỗi khi mua

Nhôm A5052: chọn O, H32 hay H34, bán kính chấn và lỗi khi mua

Cùng là nhôm A5052 nhưng tấm trạng thái O, H32 và H34 có độ bền, độ dẻo và bán kính c...

Giá nhôm tấm tuần 41/2026: SMM A00 rơi về 23.650 CNY/tấn sau lễ

Giá nhôm tấm tuần 41/2026: SMM A00 rơi về 23.650 CNY/tấn sau lễ

Sàn Thượng Hải mở cửa lại sau Quốc khánh với hai phiên giảm liền: giá nhôm thỏi SMM A...

Nghị định 344: ưu đãi chế tạo thiết bị điện trong nước từ 20/10

Nghị định 344: ưu đãi chế tạo thiết bị điện trong nước từ 20/10

Từ ngày 20/10/2026, Nghị định 344/2026/NĐ-CP mở cơ chế đặt hàng và ưu đãi cho doanh n...

Tính chất vật lý của nhôm: số liệu 1050, 3003, 5052 cho xưởng

Tính chất vật lý của nhôm: số liệu 1050, 3003, 5052 cho xưởng

Các con số vật lý của nhôm không giống nhau giữa các mác, và mỗi con số dẫn tới một q...

Giá nhôm tấm tuần 40/2026: SMM A00 giảm còn 24.030 CNY/tấn

Giá nhôm tấm tuần 40/2026: SMM A00 giảm còn 24.030 CNY/tấn

Giá nhôm thỏi SMM A00 giảm ba phiên liên tiếp trong tuần 40/2026, chốt 24.030 CNY/tấn...

Thị trường ô tô 8 tháng 2026 tăng nhanh nhất Đông Nam Á

Thị trường ô tô 8 tháng 2026 tăng nhanh nhất Đông Nam Á

Sau 8 tháng 2026, thị trường ô tô Việt Nam bán 432.548 xe, mức tăng cao nhất trong 6...

Nhôm tấm 3mm: trọng lượng, dung sai, chọn mác và lỗi khi mua

Nhôm tấm 3mm: trọng lượng, dung sai, chọn mác và lỗi khi mua

Nhôm tấm 3mm là độ dày được hỏi nhiều nhất trong nhóm tấm mỏng vì đủ cứng để làm thùn...

Nhôm A6061: chọn T6 hay T651, độ dày và lỗi khi mua tấm

Nhôm A6061: chọn T6 hay T651, độ dày và lỗi khi mua tấm

Nhôm A6061 là hợp kim nhôm–magie–silic hoá bền bằng nhiệt luyện, được dùng nhiều nhất...

Cước vận tải biển nội Á lập đỉnh 5 tuần liền trước Golden Week

Cước vận tải biển nội Á lập đỉnh 5 tuần liền trước Golden Week

Chỉ số cước container nội Á của Drewry chốt ngày 24/9/2026 ở 1.491 USD/40ft, tăng 6%...

Giá nhôm tấm tuần 39/2026: SMM A00 giữ 24.240 CNY/tấn

Giá nhôm tấm tuần 39/2026: SMM A00 giữ 24.240 CNY/tấn

Giá nhôm thỏi SMM A00 chốt tuần 39/2026 ở 24.240 CNY/tấn, cao hơn 60 CNY/tấn so với t...